If a pipe bursts in your kitchen, your homeowners policy likely has you covered. If a nor'easter pushes storm surge into your basement, it almost certainly doesn't. Standard homeowners insurance excludes flood damage, and on Long Island, where winter storm season brings coastal flooding, heavy rain, and rapid snowmelt, that gap can be an expensive one to discover after the fact.
Why Standard Homeowners Insurance Doesn't Cover Flood Damage
Homeowners policies typically cover water damage from a source inside your home, a burst pipe, an overflowing appliance, or a roof leak. They exclude flooding, which insurers define as water entering your property from an outside source: rising rivers, storm surge, or heavy rain overwhelming the ground's ability to absorb it. That distinction surprises many homeowners, usually after a claim gets denied. Homeowners must purchase flood coverage separately, either through the National Flood Insurance Program (NFIP) or a private flood insurer.
Long Island's Winter Flood Risk Isn't Hypothetical
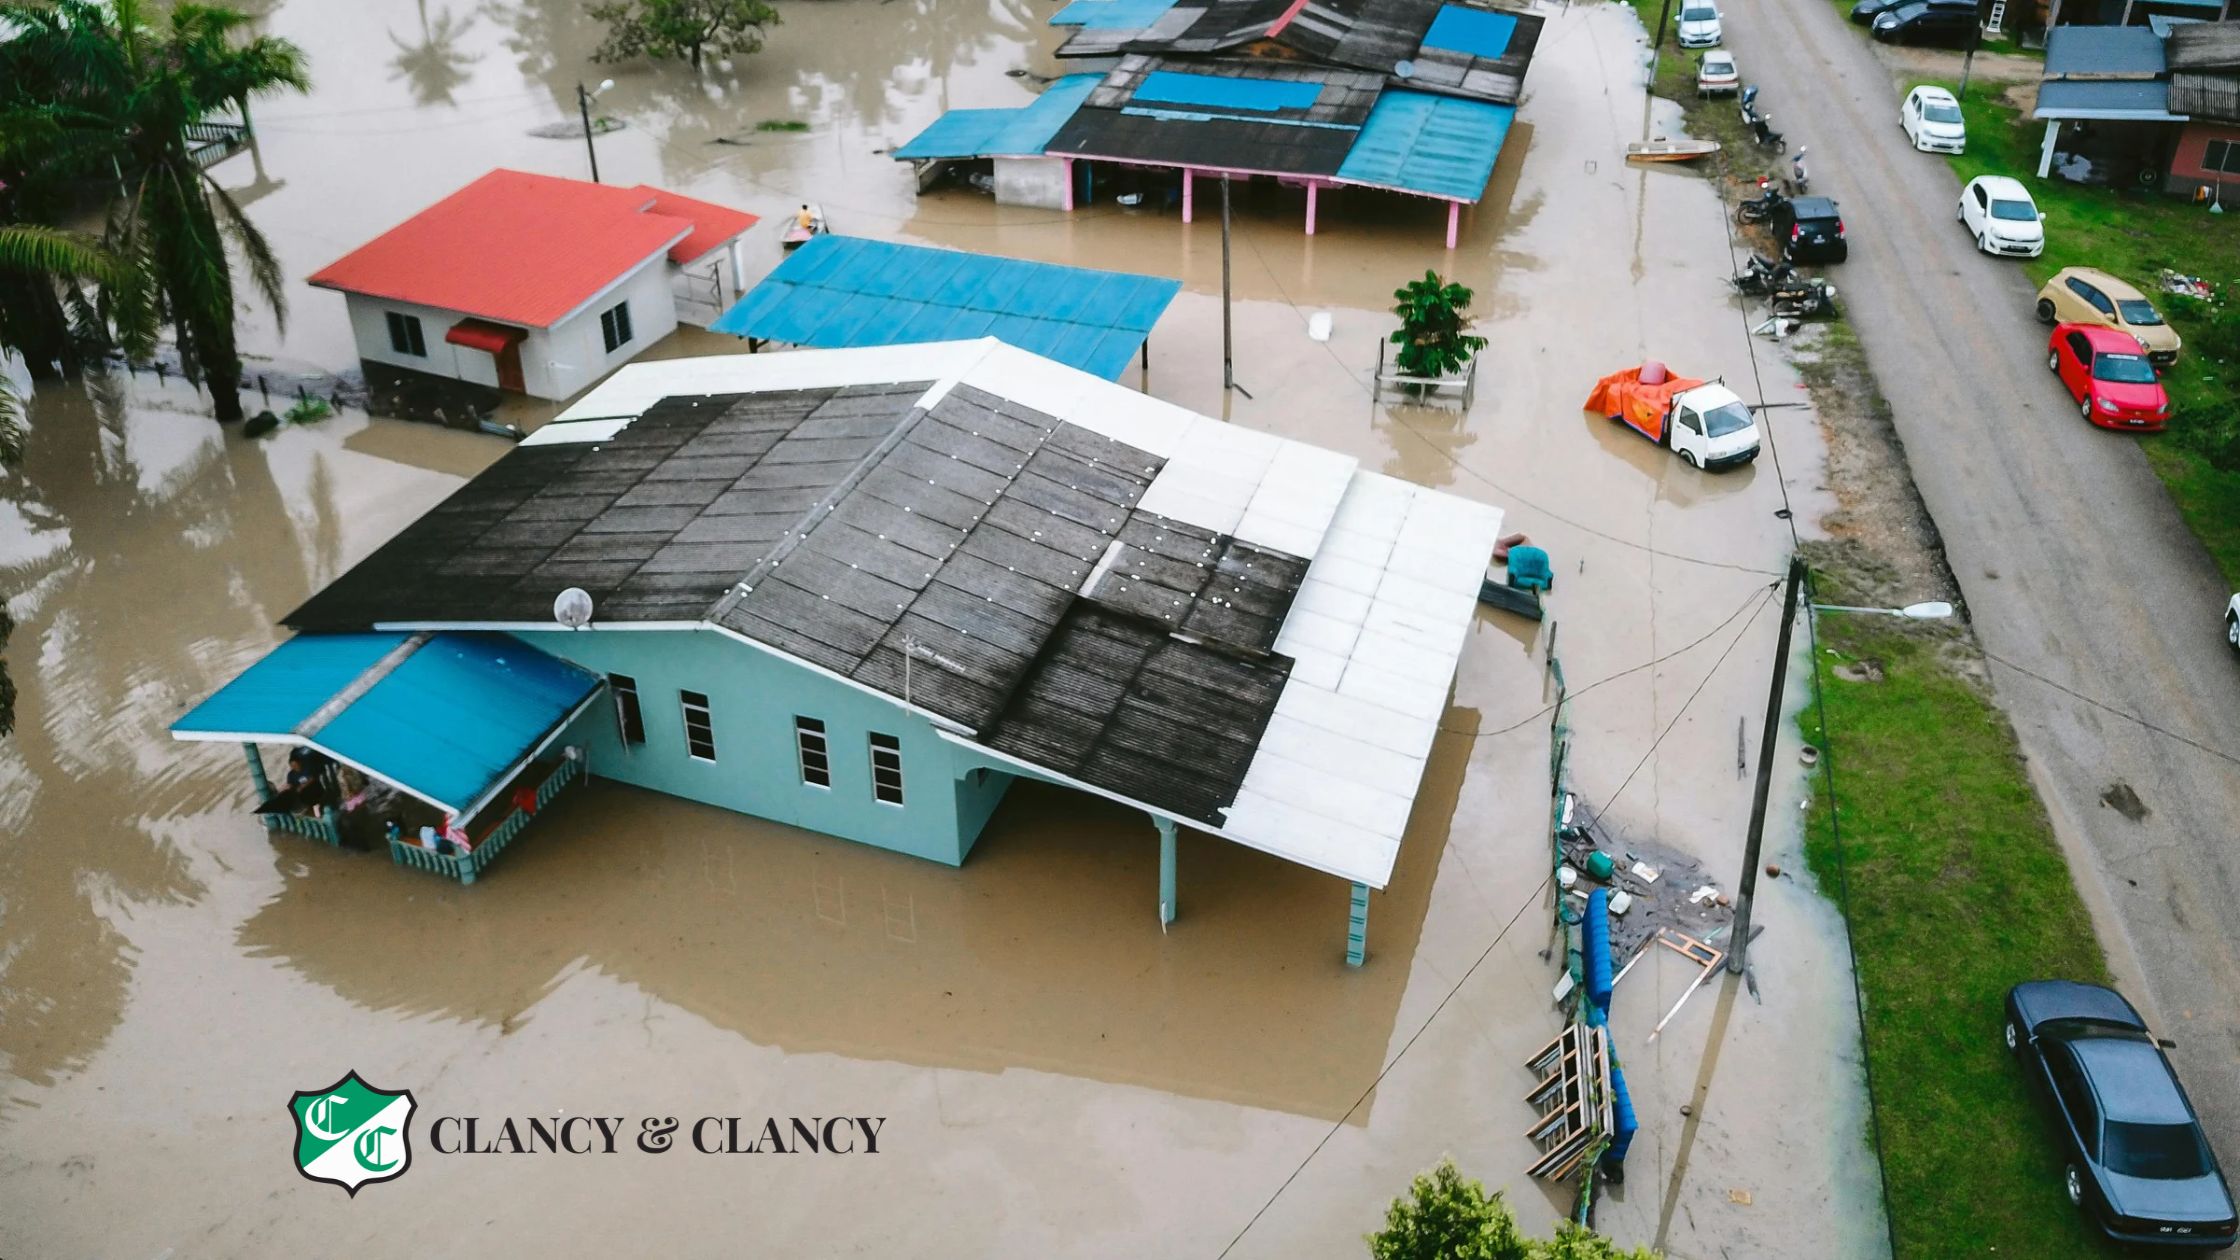
Long Island's South Shore, in particular, sees recurring coastal flooding every winter storm season. Nor'easters bring a combination of heavy rain, storm surge, and high tides that regularly push water into streets, yards, and basements across Nassau and Suffolk counties, sometimes with only a day or two of warning. Homes near canals, bays, and the shoreline face the most direct exposure, but heavy rainfall combined with high tide can cause street and basement flooding well beyond the immediate waterfront.
What Flood Insurance Actually Covers
NFIP policies split coverage into two parts: the building itself and its contents. For a single-family home, NFIP building coverage tops out at $250,000, with contents coverage up to $100,000. That covers structural elements like flooring, drywall, and electrical systems, along with furniture, appliances, and other belongings, subject to the policy's specific terms and exclusions. Private flood insurance is also available and can offer higher limits or coverage NFIP policies don't include, worth comparing if your home's value exceeds NFIP's caps.
The 30-Day Waiting Period: Why Timing Matters Now
Here's the detail that makes "before winter" more than a marketing angle: NFIP flood insurance policies have a standard 30-day waiting period before coverage takes effect. If you wait until a storm is in the forecast to buy a policy, it's too late. The main exceptions are purchasing flood insurance at a mortgage closing or during the window after a flood map revision. Private flood insurers often have shorter waiting periods, sometimes as little as 10 to 14 days, which is worth asking about if you're shopping close to storm season.
NFIP's federal authorization is currently scheduled to expire September 30, 2026. Congress has passed short-term extensions repeatedly in recent years, but if authorization lapses without a new extension, the program's ability to issue new policies could be temporarily affected. Confirm current status before this article goes live and adjust this section accordingly.
Homeowners, Renters, and Flood Insurance: Closing the Gaps
Flood insurance isn't a replacement for homeowners or renters insurance; it fills a specific gap those policies leave open. If you rent on Long Island, your landlord's policy won't cover flood damage to your belongings either, and renters flood policies are typically available at lower coverage limits and costs than homeowners flood policies. Whether you own or rent, it's worth asking whether your property sits in a FEMA-designated flood zone, since that affects both your risk and, in some cases, whether a lender requires coverage.
How to Get Flood Insurance Coverage for Your Long Island Home
As an independent brokerage, we're not limited to a single flood insurance provider. We can help you compare NFIP and private flood options, walk through your property's specific flood risk, and get a policy in place well ahead of the winter storm season, not after the first nor'easter warning goes out.
Ready to close the gap before winter storm season hits? Get a flood insurance quote or contact our team to review your current homeowners coverage.
Also read: What Is Homeowners Insurance and What Does It Cover?
Contact Us
Frequently Asked Questions (FAQs)
Is flood insurance required in New York?
Flood insurance isn't required by New York state law, but lenders must require it for federally backed mortgages on properties in FEMA-designated high-risk flood zones (Special Flood Hazard Areas). Outside those areas or without a federally backed mortgage, coverage is optional, though flooding can happen outside mapped high-risk zones too.
What does flood insurance cover that homeowners insurance doesn't?
Flood insurance covers damage from water entering your property from an external source, like storm surge, overflowing waterways, or heavy rain the ground can't absorb. Standard homeowners insurance excludes this and only covers water damage from internal sources like burst pipes or appliance failures.
How much does flood insurance cost?
Cost depends on factors like your property's flood zone designation, elevation, coverage amount, and whether you choose NFIP or private coverage. Rather than guess at a number, the most reliable way to know your actual cost is a property-specific quote, since flood risk varies significantly even between neighboring homes.
How do I get a flood insurance quote for my Long Island property?
Contact our team at (516) 689-1989 or use our online quote form. We'll review your property's flood zone status and compare NFIP and private options to find the right fit before winter storm season arrives.
References
- FEMA / National Flood Insurance Program: https://www.fema.gov/flood-insurance
- NFIP flood zone maps: https://msc.fema.gov
- National Weather Service, New York NY/Upton forecast office: https://www.weather.gov/okx/